India leads APAC in Branded Residences at INR 92,000 Crore: NOESIS
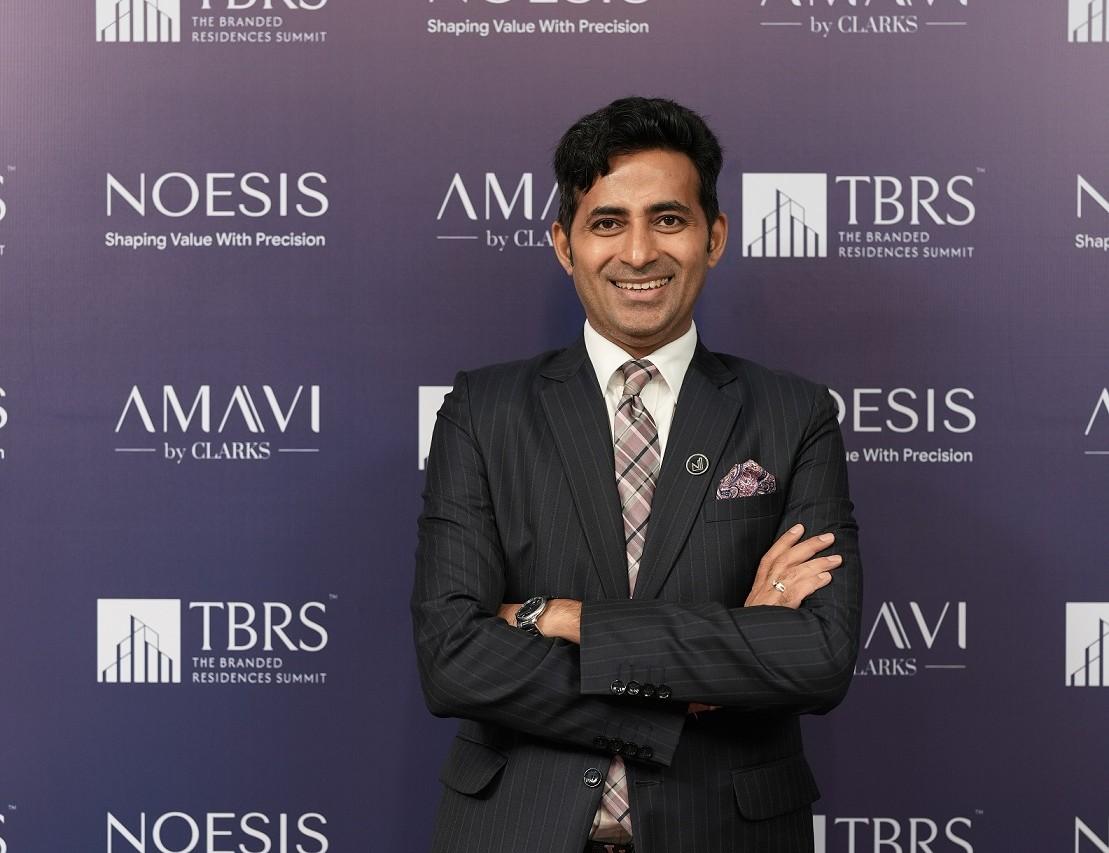 Nandivardhan Jain, Founder and CEO, NOESIS Hotel Advisors; Curator, TBRS
According to the report, 47 projects are confirmed and expects count of 85 by 2028, spread across 28 markets.
The Branded Residences Summit 2026 (TBRS 2.0), presented by Amavi by Clarks and curated by NOESIS Hotel Advisors, concluded at JW Marriott Mumbai Sahar on October 8. Over two days it brought together 350 delegates, including 250 developers, 28 international and Indian brands, more than 50 speakers and six of the funds and banks that finance Indian real estate.
The summit opened with an address by NOESIS Founder and CEO Nandivardhan Jain and the launch of The Landscape of Branded Residences in India, Edition 3, the new NOESIS report. The new report values India’s branded residences market at about INR 92,000 crore (USD 9.7 billion), the highest in Asia-Pacific. India holds 21% of the region’s USD 45.3 billion branded value from just 15% of its units, ahead of Vietnam at USD 8.0 billion.
For most of the last decade, branded residences in India were a niche category, led by a few pioneering developers in a handful of metros. Buyers and lenders were still testing whether a brand could hold a premium in Indian real estate. The last three years settled that question. The report now tracks 38 projects operational or launched, totalling 10,452 homes. Supply rose 3.1 times in 2025 alone, from 1,015 to 3,181 units. The 5,156 homes launched since January 2025 are double the previous seven years combined. Annual transaction value has grown 49% a year since 2019, with INR 47,278 crore transacted since 2018. Buyers have absorbed 68% of all branded supply launched to date.
NOESIS tracking counts 47 confirmed projects and expects 85 by 2028, spread across 28 markets. The non-metro share rises from 8% of projects to 45% of the next wave, across markets such as Goa, Alibaug, Rishikesh, Bhubaneswar and Mohali. Demand is in place to absorb it: India now has 19,877 ultra-high-net-worth individuals, up 63% since 2021.
Jain then took delegates through how a branded residence behaves as an asset at each stage of its life. At design, the brand shapes the product itself: planning, amenity programme and the arrival and shared spaces that carry the brand promise. At development, brand standards set the specification, the construction cost and the delivery timeline, so the brand decision has to be made before the drawings are frozen. In operation, service delivery, maintenance charges and owners’ association economics decide whether the promise made at sale still holds.
Branded homes sell at an average 32% premium over comparable catchment projects, led by Pune at 44% and Kolkata at 42%. They also sell faster. Faster absorption brings collections forward, reduces the debt a project carries through construction and lifts returns on the same land. Jain’s point to developers was direct: the premium comes from feasibility, positioning and operator fit, not from the logo.
Day One of the summit followed a project in the order it is actually built, from land to underwriting. It began with BRIM, the invitation-only Branded Residence Intensive Masterclass led by NOESIS, followed by a closed-door series in which YOO, Amavi by Clarks and Moricon Consultants set out what makes a brand say yes, or walk away. The say also showcased knowledge sessions featuring Atul Chordia, Founder and Chairman of Panchshil Realty, Nandivardhan Jain, senior leaders from Accor, Banyan Group, Wyndham Hotels & Resorts and The Ascott Limited, M3M India, Amavi by Clarks and Dalcore, Navdeep Sardana of Whiteland Corporation, and Kalpesh Mehta of Tribeca Developers.
Day Two moved from planning to delivery. Daniel von Barloewen, Senior Vice President, Accor One Living, opened with a keynote on the design, sales and operating principles that keep a branded residence valuable. At the Capital Roundtable, Motilal Oswal Alternates, Certus Capital, TCG Real Estate, HDFC Bank, ICICI Prudential and ASK Property Fund laid out what money will and will not underwrite in the category. The knowledge sessions of day two featured development heads from Marriott International, Radisson Hotel Group, Accor, Hyatt and Oberoi Hotels & Resorts, NOESIS COO Vijay Bhandari, Amavi by Clarks, Mahindra Holidays & Resorts, Olive by Embassy, Atmosphere Hotels & Resorts, AMPA Group, Whiteland Corporation, Panchshil Realty, M3M, IHCL and Gulshan Group, YOO, Pininfarina, Brand & Co., The Charcoal Project, Xplore Lifestyle Solutions, Sarovar Hotels & Resorts, Moricon Consultants and Royal Orchid Hotels.
Feasibility comes before the brand. The report finds the strongest sell-through where the brand tier, the operator and the measured premium are matched to the site. That match has to be made before a logo is chosen.
Capital reads the whole structure. The brand agreement, the sales plan and the debt structure are one decision for a lender. Debt belongs in the first conversation, not the last.
Hotel brands are moving in. Non-hospitality brands hold 73% of Indian branded units against about 20% globally. NOESIS expects hotel groups to narrow that gap sharply over the next 24 months.
Jain said, “For two days, India’s developers, brands and capital tested this category against hard numbers. Indian buyers have settled one question: they will pay for a brand and they buy faster. The projects that take India to 85 by 2028 will be judged on what comes after the logo. Feasibility done before the brand is chosen. A partner picked for fit, not fame. Service run well for thirty years. That is the move from logo to lifetime value.”